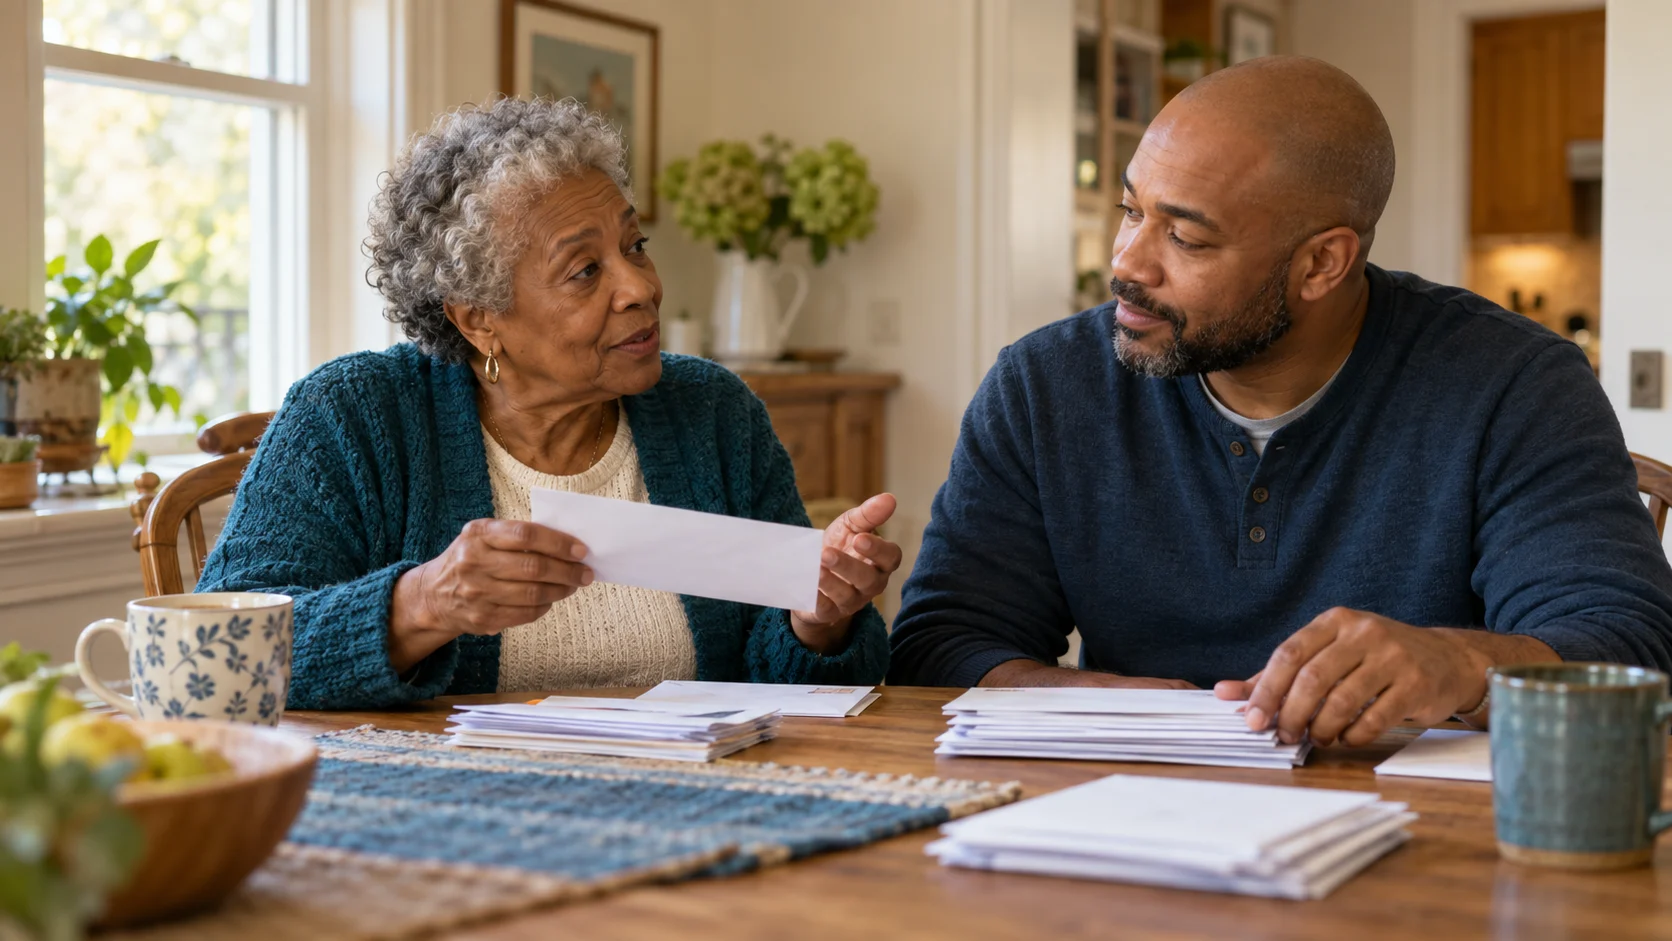
It often happens by accident. You're visiting a parent, you move a stack of mail off the kitchen counter, and you notice the red print. A late notice. Then another. Maybe a final warning from the utility company, tucked underneath a catalog.
The discovery can bring up a lot at once: worry about what else has been missed, concern about what it might mean for your parent's memory or health, and uncertainty about how to bring it up without hurting their pride.
This article walks through what to do next. It starts with the conversation, because how you begin often decides whether your parent lets you help.
Start With the Conversation, Not the Paperwork
Your parent has probably paid their own bills for fifty years or more. Finding out that things have slipped can feel embarrassing or frightening for them, too. Before you open a single envelope, think about how to raise it.
- Choose a calm moment. Not in front of other relatives, and not when anyone is rushed or tired.
- Lead with care, not alarm. Something like, "I noticed a couple of notices in the mail and wanted to see if I can help sort them out" goes further than "Why haven't you paid these?"
- Ask, don't take over. It's their money and their decision. Ask what's been getting in the way. Is it eyesight, confusing online accounts, too much mail, or something else?
- Agree on a next step together. Even a small one, like going through the mail side by side on Saturday.
If your parent says no, don't force it. Leave the door open, and try again another day. In the meantime, watch for urgent signs such as shutoff notices, which may need quicker action.
Make a Dated Inventory
Once you have permission, gather everything in one place. Sort the mail and any bills you can find into a simple list. For each one, note:
- Who the bill is from
- What it's for
- The amount due and any late fees
- The due date, and how overdue it is
- Whether it's a regular bill, a one-time charge, or a collection notice
- The date you added it to the list
Writing the date you found each item matters more than it sounds. It helps you track what you've followed up on and when, which is useful if there's a dispute later.
Keep the list somewhere you and your parent can both see it, such as a folder or a notebook kept by the phone.
Sort Out What's Urgent
Not everything needs to be handled today. Put the items in order so you can focus on what has real consequences first.
Handle first
- Shutoff notices for heat, electricity, water, or phone
- Health insurance or Medicare-related premiums
- Homeowners or renters insurance, and property taxes
- Rent or mortgage
Handle soon
- Medical bills and pharmacy accounts
- Credit cards and loans with growing late fees
Check carefully
- Collection notices, especially for debts your parent doesn't recognize
- Charges or subscriptions they don't remember signing up for
- Anything that asks for payment by gift card or wire transfer
That last group is worth a second look. Missed bills sometimes travel with scams, and an unfamiliar charge can be the first sign that someone is taking advantage of your parent. If something seems wrong, don't pay it until you've confirmed it's real.
Get the Right Kind of Access
Companies usually won't discuss an account with anyone but the account holder. To help, you'll need the right kind of permission, not just your parent's password.
- Call together. For many companies, the simplest route is to call with your parent on the line so they can give permission for you to speak.
- Ask about authorization forms. Utilities, banks, and insurers often have their own forms to add an authorized person to an account.
- Talk with an attorney about power of attorney. If your parent wants longer-term help, a financial power of attorney gives a trusted person legal authority to act. An elder law attorney can explain the options.
- Avoid using their login without permission. Even with good intentions, it can create problems with the bank and with family trust.
Decide Who Handles What
Once the urgent items are handled, agree on how things will work from here. Be specific.
- Who opens and sorts the mail, and how often?
- Who pays which bills, and from which account?
- Which bills can be set to pay automatically?
- Who keeps the list up to date?
- Who should a company call if there's a problem?
If several siblings are involved, put this in writing so everyone knows their role. One clear owner for each task is better than everyone assuming someone else has it covered.
Look at the Bigger Picture
Overdue bills are sometimes simply a sign that the paperwork has become too much. But they can also be an early sign of memory changes, vision problems, depression, or difficulty managing daily life more broadly. If bills are slipping, it's worth gently noticing whether other things are, too: medications, meals, appointments.
If you're worried, mention it to your parent's doctor, who can look at the whole picture.
How Reflections Can Help
Our bill payment support services are designed to help older adults stay on top of their bills while keeping as much independence as possible. We start with an in-home assessment, build a plan that fits how your parent likes to handle money, help set up reminders and automatic payments through their bank, and keep an eye out for unusual activity.
If you've found a pile of overdue notices and aren't sure where to begin, call Reflections at 315-497-7200 or contact us. We'll help your family take the next step calmly.
This article is general information, not legal or financial advice. For questions about power of attorney or specific debts, please speak with a qualified professional.
FAQ
How do I talk to my parent about unpaid bills?
Choose a calm, private moment and lead with an offer to help rather than criticism. Ask what's been getting in the way, and agree on one small next step together, such as going through the mail side by side.
Can I call a company about my parent's overdue bill?
Usually only with your parent's permission. Many companies will speak with you if your parent joins the call, or if they complete an authorization form adding you to the account.
Which overdue bills should we pay first?
Start with anything that threatens essentials, such as shutoff notices, insurance premiums, housing payments, and property taxes. Check unfamiliar charges or collection notices carefully before paying, since they can be signs of a scam.